

Like the Apprentice he is, Trump set off windy storms that he doesn’t understand or can control. I have been planning to write a post on the underlying theoretical disputes behind the ongoing events regarding international trade and monetary systems. Still, the pressure of circumstances just became overwhelming, and this post is about current events. The crisis entered a new dangerous phase due to the US-China full-blown trade war, and the scare that markets seemingly signalled a rotation out of US assets, stocks, bonds and the dollar.
US-CHINA DECOUPLING?
The White House clarified that the tariffs on all imports of goods from China are 145%, not 125%, including the 20% stemming from the first Trump mandate that Biden maintained. In further retaliation, China raised its tariffs on US imports of goods to 125%, declaring that whatever the US does, it will not increase them further. Trump mentioned he is waiting for a call from Xi to begin negotiations, but any Chinese initiative will start at a lower level, infuriating the vulnerable ego of the Apprentice. Perhaps, over time, with devastating consequences for the US stock market and several large firms heavily reliant on production in China, the US will have to initiate de-escalation. The significant risk is that a stalemate could develop, leading to a real decoupling of the two economies, with vast repercussions for the world. In any case, it is difficult to envision tariffs and other barriers completely disappearing from the high levels already attained. The Chinese authoritarian regime is better positioned than the nascent one in the US to impose pain and sacrifices on their populations in a full-scale trade war. Destroying TikTok is not equivalent to Apple (90% of iPhones are made in China) or Tesla (one-third of profits come from China)... This consideration comes even before assessing the potential for China to halt purchases of new Treasuries or begin selling part of its massive stock of them...
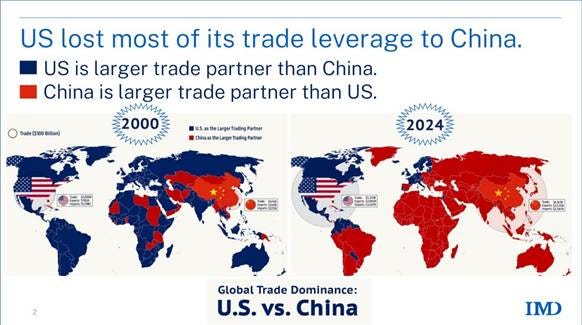
Any significant change in the US-CHINA trading flows will trigger spillovers to third countries. The US exported to China (2024) 143.5 billion USD of goods (0.6% of its GDP), and China exported to the US 439 billion (2.9% of its GDP). From 2000 to 2024, China replaced the US as the main trading partner of most countries in the world (slide)
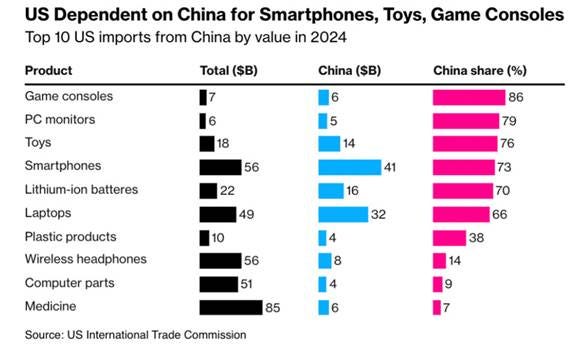
China emerged as the world's largest producer of manufactured goods, accounting for 31.6% in 2024, compared to 15.9% for the US, which has a significant reliance on various Chinese imports (refer to the red bars in the following slide).
If China experiences a sharp decline in its exports to the US, it will make every effort to boost exports to other trading partners. Given China's increasing industrial overcapacity and the necessity to export more, the anticipated China Shock 2.0 will exert further pressure on the EU. The EU will be compelled to enhance or implement new safeguard clauses to mitigate this potential tsunami. Therefore, I find it strange that the UK Trade Minister and the Spanish Prime Minister both coincidentally visited China, asking for increased trade with China in response to US policies!
The global consequences of a significant trade split between the US and China will be profoundly felt. Naturally, this will reduce global trade and economic growth. The Euro Area will be particularly impacted. In 2024, the EA exported $213 billion worth of goods to China (1.5% of its GDP), while China exported $ 518 billion to the EA (3.4% of its GDP).
The U.S. policy shift is likely to lead to a recession in both the U.S. and the Euro Area, particularly given its weak starting point. The renowned five German Institutes of Economics recently published a report sharply revising the country’s 2025 growth forecast to a mere 0.1%, a significant decline from the 0.8% projected in September 2024. This adjustment accounts for U.S. tariffs on steel, aluminium, and cars but does not include additional reciprocal tariffs announced by the U.S., which are currently suspended. Before the notable German “fiscal revolution” can take effect, the country will face a third consecutive year of recession in 2025.
AMERICA BECOMING LIKE A RISKY EMERGING COUNTRY?
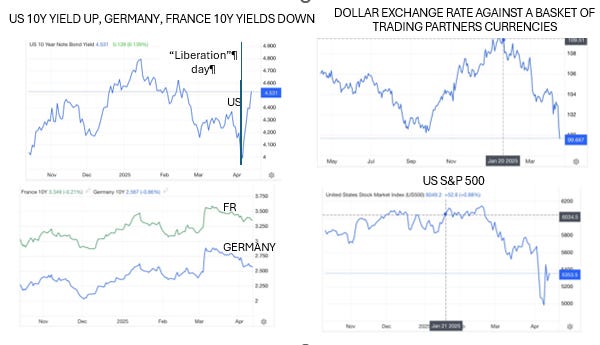
All U.S. asset prices are decreasing, including stocks, bonds, and the dollar, which is an unusual configuration (see slide 1 for data from mid-afternoon Friday, April 11th). Yields are rising while the currency is falling, a situation commonly observed in emerging markets rather than in advanced economies. Additionally, the simultaneous decline of stock and bond prices is also unsual. The markets are signalling a dangerous rotation out of dollar assets. In fact, the U.S. 10-year yield began to rise amid a sell-off of Treasuries, while European yields continued to decline.
Who is selling? Can it be already China, showing a willingness to incur losses for the sake of retaliation? It is not yet clear. Can this trigger a financial crisis like in March 2020, which is linked to the Basis Trade, which is done mostly by Hedge Funds? There are no signs of that yet, but the possibility of it happening going forward is certainly on.
It is, therefore, useful to recall what happened in March 2020, which triggered massive Fed interventions. The Basis Trade is a type of risky arbitrage involving Treasury spot and futures prices. Since the differences are usually very small, the operation must be highly leveraged (10x to 50x) by using the Repo market. One typical transaction involves purchasing Treasuries spot at price P0 and financing it through repo borrowing (for which the trader pays the repo rate r), followed by short selling the futures, where at delivery time, the investor receives FT, the futures price in the contract. Thus, the potential profit from this transaction is equal to FT – (1+r)T P0 . The value of r that makes this expression equal to zero is called the Implicit Repo Rate (IIR). Therefore, whenever the actual repo rate is below the IIR, the trader engages in the type of transaction I described, buying spot and short selling the futures, meaning he “buys the basis” (P-F). When the actual repo rate rises above the IIR, the trader performs the inverse operation: “sells the basis, " i.e., sells Treasury spot, secures them through repo lending (receiving a repo rate), and goes long (purchases) in the futures market.
The operation is not pure arbitrage because it involves several risks. First and foremost, Rollover-Risk, because the Repo market operates with overnight maturities and repo rates may become much higher and volatile as rolling over the repos becomes difficult when the market loses liquidity. This feature of the Repo markets is a very dangerous one and should not exist when repos are used to fund long maturity assets or leveraged positions. Repos amplify liquidity in good times that then suddenly disappears in moments of stress over the valuations of the assets used as collateral, The creation of inside liquidity by repos was important for the funding of the housing bubble, leading up to the 2008 crisis[1].That is one reason why Gary Gorton characterised the financial crisis as a “run on repo” [2] . The other two risks are related to margin calls, when the trader goes long on futures and to the overall risk of leveraged operations when they turn sour.
What happened in March 2020, at the start of the pandemic, when liquidity became scarce, were three things: the Treasuries market became illiquid, and prices started to decrease when many wanted to sell; second, the repo rate increased a lot and became volatile, and third, the Chicago Board of Trade in charge of the futures markets, increased margin calls. Hedge Funds were forced to sell Treasuries for the liquidity (they sold $426 in early March ) and were looking to possible huge losses from the repo rate increases. The overall situation led the FED to make massive market interventions that saved the Hedge Funds and others from huge losses. The list of those FED interventions is quite impressive:
1. Interest Rate Cuts: • On March 3 and March 15, 2020, the Fed reduced the federal funds rate by a total of 1.5 percentage points, bringing it to a range of 0%-0.25%.
2. Quantitative Easing (QE): • On March 15, 2020, the Fed committed to purchasing at least $700 billion in assets ($500 billion in Treasury securities and $200 billion in mortgage-backed securities). This program became unlimited on March 23,
3. Treasury Market Intervention: • The Fed purchased over $1 trillion in Treasury securities during Q1 2020 to address liquidity shortages and stabilize yields.
4. Lending Facilities: • Primary Dealer Credit Facility (PDCF): Relaunched on March 17, offering collateralized loans to primary dealers without a set limit. • Money Market Mutual Fund Liquidity Facility (MMLF): Launched on March 23 with $10 billion in Treasury backing, aimed at stabilizing money market mutual funds. • Municipal Liquidity Facility (MLF): Announced April 9, with capacity to purchase up to $500 billion in short-term notes issued by states and municipalities.
5. Repo Operations: • The Fed made $1 trillion in overnight repos available daily and $500 billion in longer-term repos weekly.!
The episode is a telling example of the dangerous mechanism that goes from sudden illiquidity in the repo market to the sell-off of the underlying securities, Treasuries in this case. Will it happen again this time? It´s early to tell, but the possibility is underlined by a recent academic paper that states, “We have identified the cash-futures basis trade as a potentially critical source of instability in the Treasury market. Data suggest that hedge funds currently have on the order of $1 trillion of highly leveraged long positions in cash Treasury securities tied up in this specific arbitrage trade— positions that are at risk of being rapidly unwound if these hedge funds are hit by any one of a number of different possible shocks”. [3] The authors propose as a solution a new FED facility to be “…implemented with a standing facility that acts to create a cap on the Treasury-futures basis and thereby eliminate just the most extreme spikes. If, for example, the cap was set at 25 basis points, the Fed could simply enter the market any time the basis threatened to breach the cap, buy the requisite amount of cash bonds through a conventional open market operation, and short the equivalent amount of futures via a transaction with a futures exchange. Indeed, such a facility would be closely analogous to a standing repo facility that aimed to cap spikes in repo spreads.”
The US bond market situation may worsen if the imminent tax cuts legislation goes beyond the mere extension of previous reductions. This would imply a clear aggravation of the budget deficit. The Trump Administration's spin is that the revenue from tariffs will offset the tax cuts, but that contradicts the declared intentions of bringing them down after negotiations.
Regarding stock prices, the potential damage caused by the transmission of the Trump chaos surfaced against a backdrop of already overstretched valuations, characterised by very high price/earnings ratios and a substantial market capitalisation-to-GDP ratio (the Buffett Indicator).
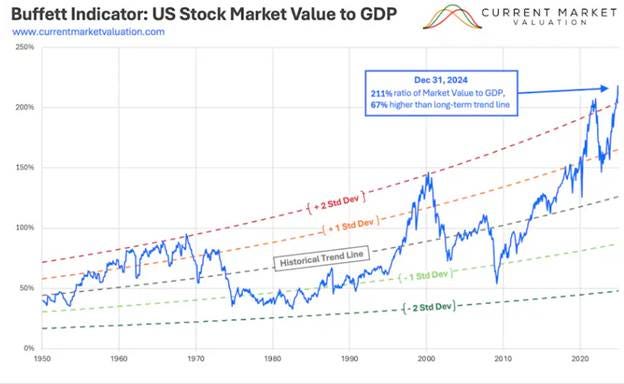
Buffet, the renowned savvy investor, having built up his cash position on the eve of the two previous stock market crashes, did it again this time and sold a lot of shares in his portfolio since last (e.g. more than 50% of Apple and a lot from Bank of America) accumulating a cash position around $350 billion, 30% of the portfolio. It is also relevant to recall that the US International Investment Position (IIP), its assets abroad minus its liabilities to the rest of the World, is negative to the tune – 88% of GDP! For comparison, the IIP of the Euro Area and China are positive, 11% and 19%, respectively. Foreigners are estimated to hold around 30 % of the US stock market and 24% of its Treasury bonds. The possibility of the worldwide financial system being threatened by a significant rotation out of American assets is too scary to contemplate. So, most market players still believe that this will all go away with possible changes in Trump policies and, especially, with FED interventions. Hopefully, that will happen, but the situation has become too serious and dependent on China´s behaviour. The US lost all its soft power, now lacking credibility and the world's trust as a reliable partner.
Regarding the FED, markets still expect it to save the day by cutting rates three or four times this year and purchasing Treasuries and other assets. They forget that tariffs, even if they remain at 10%, will have a price impact that will increase measured inflation this year and next. This type of stagflation shock is more difficult for central banks to navigate. In my view, the FED will need to keep rates on hold for the rest of the year. It should promptly halt the shrinking of its Treasuries portfolio (QT) and be prepared to make liquidity injections as the situation may require. Fortunately, since 2019, the FED has made the “floor system” for implementing monetary policy permanent, which has the significant advantage of allowing liquidity injections without affecting the stance of policy regarding the policy interest rate, fixed by the CB in a floor system. Regrettably, the ECB chose to reject the “floor system” last year, opting for a future lean balance sheet with a promise of providing bank reserves “on demand. " However, there is still excess liquidity in the banking sector, which currently allows the ECB to control the overnight market rate. Additionally, by 2028, the ECB will need to start creating a “structural portfolio” (permitted by the 2024 decision) that will assist in steering the money market rate. Contrary to the FED, what is now required is implementing two further cuts in the policy rate, which the market expects with high probabilities.
In any case, the world economy is in uncharted territory, and a global recession cannot be ruled out.
The Apprentice is also now in trouble and, as in Goethe´s poem, cries for help: " Sir, my need is sore/ Spirits that I´ve cited/ My commands ignore.” [4]
[1] See Bayoumi, T. (2017) ibid , page 73.
[2] See, for instance, Gary Gorton (2010) “Slapped by the Invisible Hand: The Panic of 2007” Oxford U P
[3] A. Hashyap, J. Stein, J, Wallen and J. Younger (2025) “ Treasury Market Dysfunction and the Role of the Central Bank” Brookings Papers on Economic Activity 27 March, 2025
[4] J. Goethe (1779), Der Zauberlehring, (The Sorceresr´s apprentice, translated by Edwin Zeydel, 1955)